The first 5 questions are solved below. Log in as a CLASS 12 SECOND PUC student to reveal solutions for the rest of this paper.
Log In →
Q1
mcq
1 mark
In the absence of partnership deed, profits or losses must be shared in
-
A.
Capital proportion
-
B.
Equal proportion
-
C.
Agreed proportion
-
D.
Any other proportion
Correct Answer: B —
Solution
According to the Indian Partnership Act, 1932, in the absence of a partnership deed, all partners are entitled to share profits and losses equally. Option A, C, and D are incorrect because they require a prior agreement or specific deed provisions which are absent in this case.
Q2
mcq
1 mark
The old profit sharing ratio among Ramesh, Sathish and Ravish were 2:2:1. The new profit sharing ratio after Sathish's retirement is 3:2. The gain ratio of continuing partners is
-
A.
3 : 2
-
B.
2 : 1
-
C.
1 : 2
-
D.
1 : 1
Correct Answer: C —
Solution
The gain ratio is calculated as New Ratio - Old Ratio. Old ratio of Ramesh and Ravish was 2:2:1 (Ramesh=2/5, Ravish=1/5). After Sathish retires, the new ratio is 3:2 (Ramesh=3/5, Ravish=2/5). Gain of Ramesh = $3/5 - 2/5 = 1/5$. Gain of Ravish = $2/5 - 1/5 = 1/5$. Therefore, the gain ratio is 1:1. Wait, calculating again: The old ratio was 2:2:1. Ramesh: 2/5, Sathish: 2/5, Ravish: 1/5. New ratio: 3:2 (3/5 and 2/5). Ramesh's Gain: $3/5 - 2/5 = 1/5$. Ravish's Gain: $2/5 - 1/5 = 1/5$. The ratio is 1:1. However, checking the provided options, if the new ratio is 3:2, the gain ratio is 1:1. Given the options provided, there might be a typo in the question's target options, but mathematically it is 1:1.
Q3
mcq
1 mark
A company issued 2,000, 8% debentures of `100 each at par value redeemable at 10% premium. 8% stands for :
-
A.
Rate of dividend
-
B.
Rate of tax
-
C.
Rate of TDS
-
D.
Rate of interest
Correct Answer: D —
Solution
In accounting for debentures, the prefix (e.g., 8%) denotes the fixed rate of interest payable on the face value of the debenture. It is not a dividend (which applies to shares), nor tax, nor TDS.
Q4
mcq
1 mark
Which of the following is not required to be prepared under the Companies Act?
-
A.
Fund flow statement
-
B.
Balance sheet
-
C.
Report of directors and auditors
-
D.
Statement of profit and loss
Correct Answer: A —
Solution
Under the Companies Act, companies are required to prepare a Balance Sheet, Statement of Profit and Loss, and reports of directors and auditors. A 'Fund Flow Statement' is not a mandatory financial statement under the Companies Act for general statutory filing.
Q5
mcq
1 mark
Tangible assets of a company increased from ` 4,00,000 to ` 5,00,000. What is the percentage of change?
-
A.
20%
-
B.
25%
-
C.
33%
-
D.
50%
Correct Answer: B —
Solution
Percentage change = $\frac{\text{New Value} - \text{Old Value}}{\text{Old Value}} \times 100$. Calculation: $\frac{5,00,000 - 4,00,000}{4,00,000} \times 100 = \frac{1,00,000}{4,00,000} \times 100 = 25\%$.
Q6
short answer
1 mark
Goodwill is an ______ asset.
Q7
short answer
1 mark
Partner's loan is _____ to the realisation account.
Q8
short answer
1 mark
Profit on forfeiture of shares is transferred to ______ account.
Q9
short answer
1 mark
Analysis and interpretation are _____ to each other.
Q10
short answer
1 mark
Cash flow statement also helps in ______ of cash flows.
Q11
short answer
5 marks
Match the following: A (a) Right of a new partner, (b) Common seal, (c) Redemption of debenture, (d) Liquidity ratio, (e) Cash flow statement prepared. B (i) As per AS-3, (ii) Short term in nature, (iii) As per AS-1, (iv) Share in future profit, (v) Discharge of liability, (vi) Official signature of the company.
Q12
short answer
1 mark
State any one content of the partnership deed.
Q13
short answer
1 mark
Deceased partner may be paid in one lumpsum or instalments with interest. (State true/false)
Q14
short answer
1 mark
Mention any one way of dissolution of partnership firm.
Q15
short answer
1 mark
Give an example for non-current liabilities.
Q16
short answer
1 mark
Expand RONW.
Q17
short answer
2 marks
State any two differences between fixed capital method and fluctuating capital method.
Q18
short answer
2 marks
Give the journal entry when retiring partner is paid cash in full.
Q19
short answer
2 marks
Name any two categories of share capital.
Q20
short answer
2 marks
Write any two objectives of financial statements.
Q21
short answer
2 marks
State any two examples of cash flow from operating activities.
Q22
long answer
6 marks
Varun and Tarun were partners in a firm sharing profits and losses in the ratio of 3:2. They admit Kiran for 1/6th share in profits and guaranteed that his share of profit will not be less than ` 25,000. The total profits of the firm was ` 90,000. Calculate the share of profits for each partner when guarantee is given by Varun and Tarun equally. Prepare Profit and Loss Appropriation Account.
Q23
long answer
6 marks
Rajesh and Rakesh are partners sharing profits and losses in ratio of 5:3. They admit Ramesh as a new partner. The new profit sharing ratio is 3:2:1 respectively. Find out the sacrifice ratio of old partners.
Reading Passage
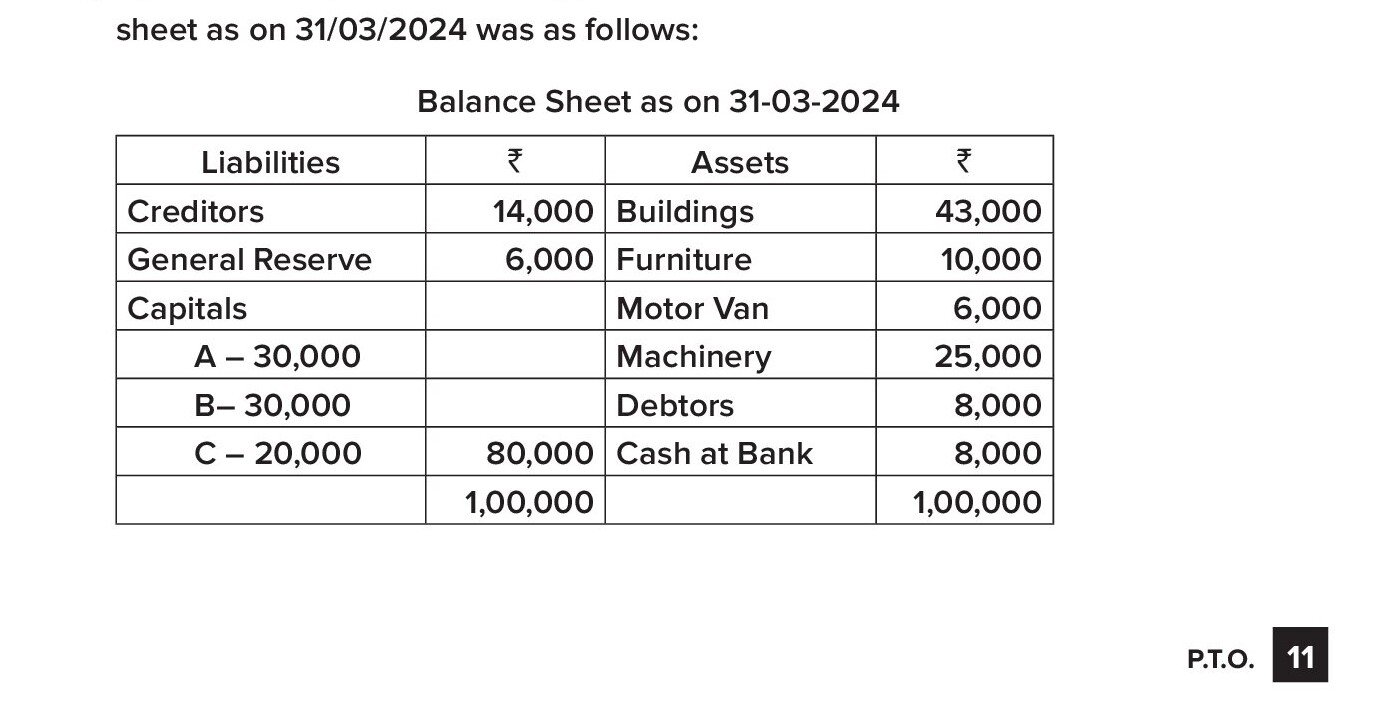
A, B and C are partners sharing profits and losses in the ratio of 5:3:2. Their balance sheet as on 31/03/2024 was as follows:
Balance Sheet as on 31-03-2024
Liabilities ` Assets `
Creditors 14,000 Buildings 43,000
General Reserve 6,000 Furniture 10,000
Capitals Motor Van 6,000
A – 30,000 Machinery 25,000
B– 30,000 Debtors 8,000
C – 20,000 80,000 Cash at Bank 8,000
1,00,000 1,00,000
'C' died on 01/10/2024 and partnership deed has provided the following:
a. Interest on capital at 10% p.a.
b. Goodwill of the firm be valued at 3 times the average profit of last four years.
Last four years profits are as follows:
2020-21 ` 13,000
2021-22 ` 12,000
2022-23 ` 16,000
2023-24 ` 15,000 (As per AS–26).
c. C's share of profit till the date of death should be calculated on the basis of last
year profit.
Q24
long answer
6 marks
A, B and C are partners sharing profits and losses in the ratio of 5:3:2. Their balance sheet as on 31/03/2024 is provided. 'C' died on 01/10/2024 and partnership deed has provided: a. Interest on capital at 10% p.a., b. Goodwill of the firm be valued at 3 times the average profit of last four years, c. C's share of profit till the date of death should be calculated on the basis of last year profit. Prepare C's executor's account.
Q25
long answer
6 marks
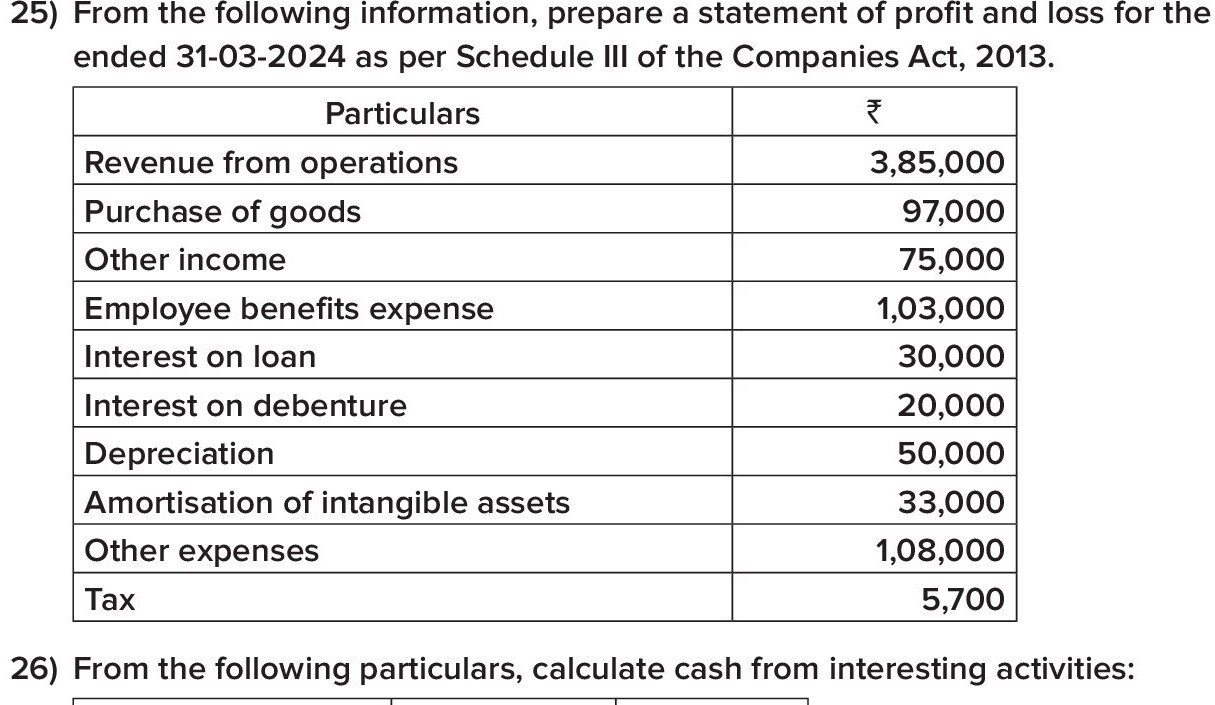
From the following information, prepare a statement of profit and loss for the year ended 31-03-2024 as per Schedule III of the Companies Act, 2013.
Q26
long answer
6 marks
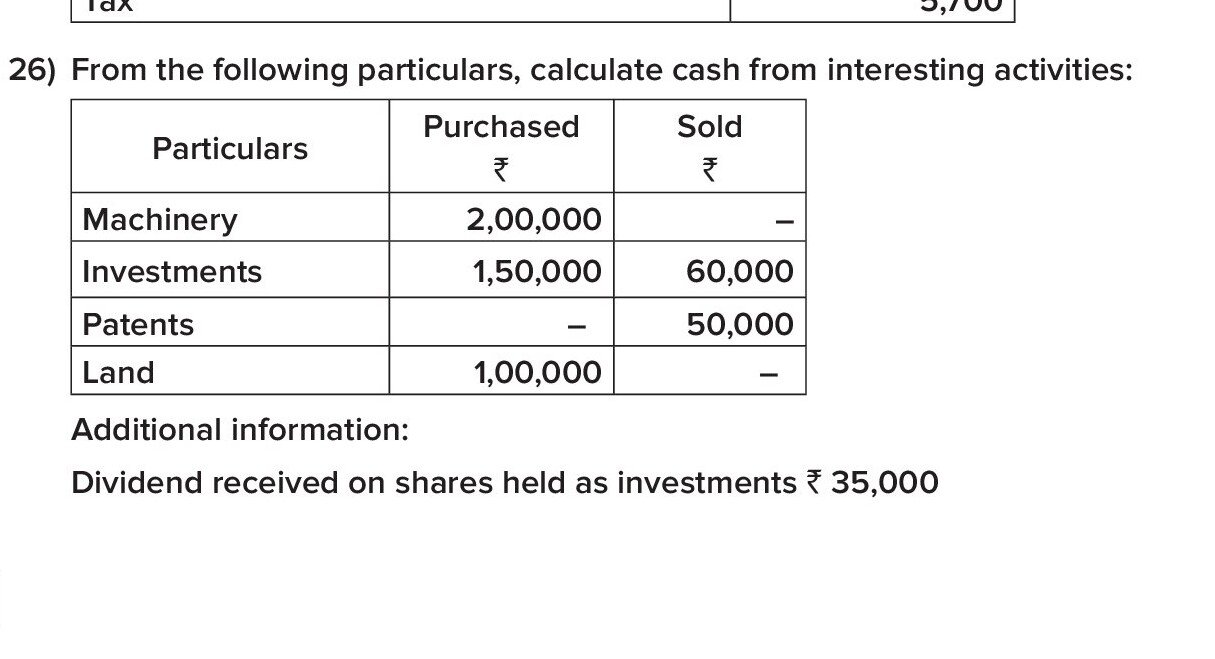
From the following particulars, calculate cash from investing activities:
Q27
long answer
12 marks
Manju, Mohan and Madhan are partners sharing profits and losses in the ratio of 2:2:1 respectively. Their balance sheet as on 31/03/2024 was as follows:
Balance Sheet as on 31-03-2024
Liabilities: Creditors ₹ 35,500, General Reserve ₹ 22,500, Capitals (Manju ₹ 50,000, Mohan ₹ 30,000, Madhan ₹ 20,000). Total ₹ 1,58,000.
Assets: Cash at Bank ₹ 20,000, Debtors ₹ 40,000 (Less PDD ₹ 2,000) = ₹ 38,000, Stock ₹ 15,000, Machinery ₹ 25,000, Furniture ₹ 10,000, Buildings ₹ 50,000. Total ₹ 1,58,000.
Madhan retired on 01/04/2024 from the firm. After retirement of Madhan, the following adjustments are to be made:
a) Stock to be increased by 20%
b) Maintain PDD at 10% on debtors.
c) Depreciate machinery and furniture by 10% each
d) Buildings are revalued at ₹ 60,000.
e) Goodwill of the firm valued at ₹ 15,000 (As per AS-26).
Prepare:
i) Revaluation Account
ii) All Partners' capital Accounts and
iii) Balance sheet as on 01/04/2024
Q28
long answer
12 marks
Sridevi and Sripriya are partners sharing profits and losses equally. Their balance sheet as on 31/03/2024 was as follows:
Balance Sheet as on 31-03-2024
Liabilities: Creditors ₹ 50,000, Bills payable ₹ 30,000, Reserve fund ₹ 10,000, Capitals (Sridevi ₹ 75,000, Sripriya ₹ 60,000). Total ₹ 2,25,000.
Assets: Cash at bank ₹ 18,000, Bills Receivables ₹ 20,000, Stock ₹ 30,000, Debtors ₹ 40,000, Building ₹ 50,000, Motor car ₹ 27,000, Furniture ₹ 40,000. Total ₹ 2,25,000.
On the above date, they decided to dissolve the firm.
Additional information:
a) Assets realised as follows: Stock – ₹ 30,400, Bills Receivables – ₹ 19,000, Furniture – ₹ 35,000, Debtors – ₹ 42,600 (with interest)
b) Sridevi took over Buildings at ₹ 60,000 and Sripriya agreed to take over motor car at ₹ 26,600.
c) All liabilities were paid in full by the firm.
d) Realisation expenses were ₹ 5,000.
Prepare:
i) Realisation Account
ii) Partner's Capital Accounts and
iii) Bank Account
Q29
long answer
12 marks
Hema Company Ltd issued 60,000 equity shares of ₹100 each at a premium of ₹ 10 per share. The amount payable are as follows:
On application ₹ 20.
On allotment ₹ 50 (including premium).
On first and final call ₹ 40.
All the shares were subscribed and the money duly received except the first and final call on 5,000 shares. These shares were forfeited and out of these only 4,000 shares are reissued at ₹ 80 each as fully paidup.
Pass the necessary journal entries in the books of the company.
Q30
long answer
12 marks
Pass necessary journal entries at the time of redemption of debentures in each of the following cases.
i) 'M' Company Ltd. issued 10,000, 8% debentures of ₹ 100 each at par and redeemable at par at the end of 5 years out of capital
ii) 'N' Company Ltd. issued 4,000, 12% debentures of ₹ 100 each at par. These debentures are redeemable at 10% premium at the end of 4 years.
iii) 'O' Company Ltd. issued 10% debentures of the total face value of ₹ 8,00,000 at a premium of 5% to be redeemed at par at the end of 4 years.
iv) 'P' Company Ltd. issued 3,00,000, 10% debentures at a discount of 5% but redeemable at a premium of 5% at the end of 5 years.
v) 'Q' Company Ltd. issued 2,000, 8% debentures of ₹ 100 each at a premium of 5% to be redeemed at par at the end of 4 years
Q31
long answer
12 marks
From the following information, prepare common size balance sheet of Vageesh Co. Ltd.
Particular: Equity share capital (31/03/2023: ₹ 8,50,000; 31/03/2024: ₹ 10,00,000), Reserves and surplus (31/03/2023: ₹ 1,00,000; 31/03/2024: ₹ 50,000), Long-term borrowings (31/03/2023: ₹ 4,50,000; 31/03/2024: ₹ 5,75,000), Short-term borrowings (31/03/2023: ₹ 1,50,000; 31/03/2024: ₹ 2,25,000), Tangible assets (31/03/2023: ₹ 7,50,000; 31/03/2024: ₹ 9,00,000), Intangible assets (31/03/2023: ₹ 4,00,000; 31/03/2024: ₹ 4,50,000), Inventories (31/03/2023: ₹ 1,00,000; 31/03/2024: ₹ 2,00,000), Other current assets (31/03/2023: ₹ 3,00,000; 31/03/2024: ₹ 3,00,000)
Q32
long answer
12 marks
From the following information, you are required to calculate:
a) Current Ratio.
b) Total Assets to debt Ratio.
c) Fixed Assets Turnover Ratio.
d) Working capital Turnover Ratio.
e) Operating Profit Ratio and
f) Book value per share.
Particulars: Revenue from operations ₹ 20,00,000, Paidup equity shares of ₹ 10/- each ₹ 5,00,000, Current Assets ₹ 4,00,000, Operating Profit ₹ 16,00,000, 13% Debentures ₹ 1,00,000, General Reserve ₹ 1,00,000, 10% preference shares of ₹ 10/- each ₹ 2,00,000, Current liabilities ₹ 2,50,000, Plant and Machinery ₹ 3,00,000, Furniture ₹ 5,00,000, Net profit after tax ₹ 1,00,000